NY Part 253 Update: Enforcement Dates, the 100-Year GWP Shift, and Next Steps
/NYSDEC delayed enforcement on six Part 253 deadlines, but 2026 data is still required, and methane-heavy sources may need to re-screen reporting thresholds.
Read MoreKeep up to date with recent company news, press releases, and important regulatory news. This is a hub for readers interested in KERAMIDA’s growth and achievements, as well as relevant global regulatory developments.
NYSDEC delayed enforcement on six Part 253 deadlines, but 2026 data is still required, and methane-heavy sources may need to re-screen reporting thresholds.
Read More
On October 14, 2026, the U.S. Environmental Protection Agency (EPA) published an interim final rule extending the Greenhouse Gas Reporting Program (GHGRP) deadline for Reporting Year 2025 (RY 2025) from October 30, 2026, to March 10, 2027 (91 FR 65112). The rule amends 40 CFR 98.3(b)(6), became effective on publication, and applies to all GHGRP source categories. This is the second extension of the RY 2025 deadline. EPA previously moved it from March 31, 2026, to October 30, 2026, as we reported in our March 2026 Client Alert.
EPA gave two reasons for the new extension. First, the Agency needs more time to consider the more than 50,000 comments it received on its September 2025 proposal to reconsider the GHGRP, and to take final action on that proposal before RY 2025 reports are due. Second, EPA stated it will not have the electronic Greenhouse Gas Reporting Tool (e-GGRT) ready in time for an October 30 deadline. EPA normally opens e-GGRT about six weeks before reports are due. For many reporters, this explains a lot. EPA has not yet released the e-GGRT reporting templates for RY 2025, so companies have been waiting without the tools they normally use to prepare, check, and load their data. Without e-GGRT and its templates, an October 30 deadline was not realistic for either EPA or the regulated community.
EPA's reconsideration proposal would eliminate reporting for 46 source categories and suspend the remaining Subpart W segments until 2034, meaning no facility would need to submit a RY 2025 report if the proposal is finalized as written. The repeated deadline extensions appear intended to let EPA finalize those revisions before any RY 2025 reports come due. The new rule supports that reading: EPA states the extension will let reporters benefit from any burden-reduction revisions it finalizes for RY 2025, and will help them avoid wasted compliance effort.
The rule changes only the RY 2025 deadline. All existing reporting, monitoring, and recordkeeping requirements under 40 CFR Part 98 remain in effect until EPA publishes a final rule on its reconsideration proposal. Facilities should keep their RY 2025 data organized and ready to submit, and should continue RY 2026 monitoring and data collection under the current rule.
Facilities should also plan for a potential March 2027 reporting crunch. If EPA ultimately keeps some or all existing obligations, RY 2025 reports would be due March 10, 2027. Under the current rule, RY 2026 reports are due March 31, 2027. That could put two annual reports due within about three weeks of each other.
Because EPA issued this rule without prior notice and comment, it is taking public comment after the fact. Comments are due November 30, 2026, under Docket ID No. EPA-HQ-OAR-2025-0186.
KERAMIDA will continue to monitor EPA's action on the GHGRP reconsideration and will provide updates as they develop. If you have questions about how these developments may affect your facility, please contact us.
The first reporting deadline of California’s Climate Corporate Data Accountability Act (SB 253) is November 10, 2026, now less than one month away.
Read MoreThe EU has finalized its simplified sustainability reporting standards. Commission Delegated Regulation (EU) 2026/1563 was published on September 21, replacing the existing ESRS annexes, and enters into force on November 10, 2026. The revised standards cut mandatory datapoints by over 60%.
EU companies and non-EU issuers with more than 1,000 employees on average and over 450 million in net turnover remain in CSRD scope. The first CSRD reports are expected in 2028 and should cover FY 2027.
Non-EU companies exceeding 450 million(euros) net turnover generated in the EU and having at least one EU subsidiary or branch with over 200 million(euros) net turnover will report under ESRS-40a (currently in draft, anticipated to be published January 2027), with first reports due in 2029, expected to cover FY 2028.
The revised ESRS applies to financial years beginning with January 1, 2027. The first report comes in 2028, but the data behind it starts on January 1. First-time reporters don’t need prior-year comparatives in year one, but FY 2027 data become the baseline. Emissions, workforce, and value chain data need consistent methods, boundaries, and controls from the start of the year.
No comparative information is required in the first reporting year.
Biodiversity (E5) and the value chain workers, affected communities, and consumers standards (S2 to S4) can be omitted for the first two years.
Most anticipated financial effects are also phased in over two to four years.
Starting in FY 2027, in-scope companies cannot require value chain partners with an average of 1,000 employees or fewer, including non-EU suppliers, to provide information beyond the short list of essential ESG data points in Annex II of the EU’s Voluntary Standard (Delegated Regulation (EU 2026/1560). Supplier data requests for 2027 should be designed around this limit.
Companies already reporting under the existing ESRS may choose between:
The existing ESRS
The ESRS, supplemented by eight specific reliefs from the revised standards
The Revised ESRS in full
Companies must state in their sustainability statement which version they applied.
Confirming whether your organization is in scope under the new thresholds.
Performing and refreshing Double Materiality Assessments against the revised standards.
Collecting, managing, and mapping data against EFRAG’s revised list of data points with a Gap Assessment and Implementation Roadmap.
Supporting companies in closing gaps in the Roadmap with additional sustainability services such as GHG Inventories, ESG training, etc.
New funding opportunities continue to become available for climate action, sustainability, resilience, infrastructure, and community-focused projects. At the same time, application windows, eligibility requirements, and available funding can vary significantly by program.
KERAMIDA's team tracks federal, state, and regional funding opportunities to help keep clients informed of programs that may support current or planned projects. Below are several opportunities to be aware of, including upcoming application deadlines and programs that remain open on a rolling or ongoing basis.
Questions about an opportunity below? KERAMIDA's team is available to help determine how a program may apply to your project. Talk to our team.
On September 1, 2026, The California Air Resources Board (CARB) released multiple resources for the CARB proposed November 10, 2026 greenhouse gas (GHG) emissions reporting deadline, required by Senate Bill (SB) 253. The key update is the introduction of two submittal options for 2026 reporting: a new voluntary Report Intake Platform, and the ability to submit reports and contact information via email.
New CARB Resources
A voluntary 2026 Report Intake Platform that entities may choose to use. Use of this platform is not mandatory. Entities may also email emissions reports and contact information to climatedisclosure@arb.ca.gov.
A video tutorial of the voluntary report intake platform
Acceptable Reporting Formats for 2026
Entities may satisfy their 2026 reporting obligation by:
Submitting an existing annual report that includes Scope 1 and Scope 2 GHG emissions.
Submitting existing Scope 1 and Scope 2 data already reported to other programs or voluntary initiatives.
Using CARB’s Draft Scope 1 and Scope 2 GHG Reporting Template for reporting Scope 1 and Scope 2 data.
Submitting a statement of non-reporting (on company letterhead) if the entity was not collecting, and was not planning to collect, Scope 1 and Scope 2 data as of December 5, 2024, when the Enforcement Notice was issued.
Emissions reports, non-reporting statements, and contact information may be submitted via the voluntary 2026 Report Intake Platform or emailed to climatedisclosure@arb.ca.gov. All emission reports or statements of non-reporting will be made public.
Key Clarifications
Minimum reporting scope: For 2026, reporting entities submitting reports are only required to provide their annual Scope 1 and Scope 2 emissions. Additional details – methodology descriptions, data sources, global warming potential (GWP) values, emission factors, organizational boundaries, disaggregated emissions data by category and gas, and any assumptions used – are optional, not required.
Reporting template is voluntary: CARB’s Draft Scope 1 and Scope 2 GHG Reporting Template, posted on October 10, 2025, may be used, but its use is not mandatory for this cycle.
CARB will still accept submissions whether or not assurance has been obtained for the 2026 cycle.
CARB is currently developing the reporting requirements for 2027, and this guidance only applies to the 2026 reporting cycle.
Contact Erica at: eskowron@keramida.com
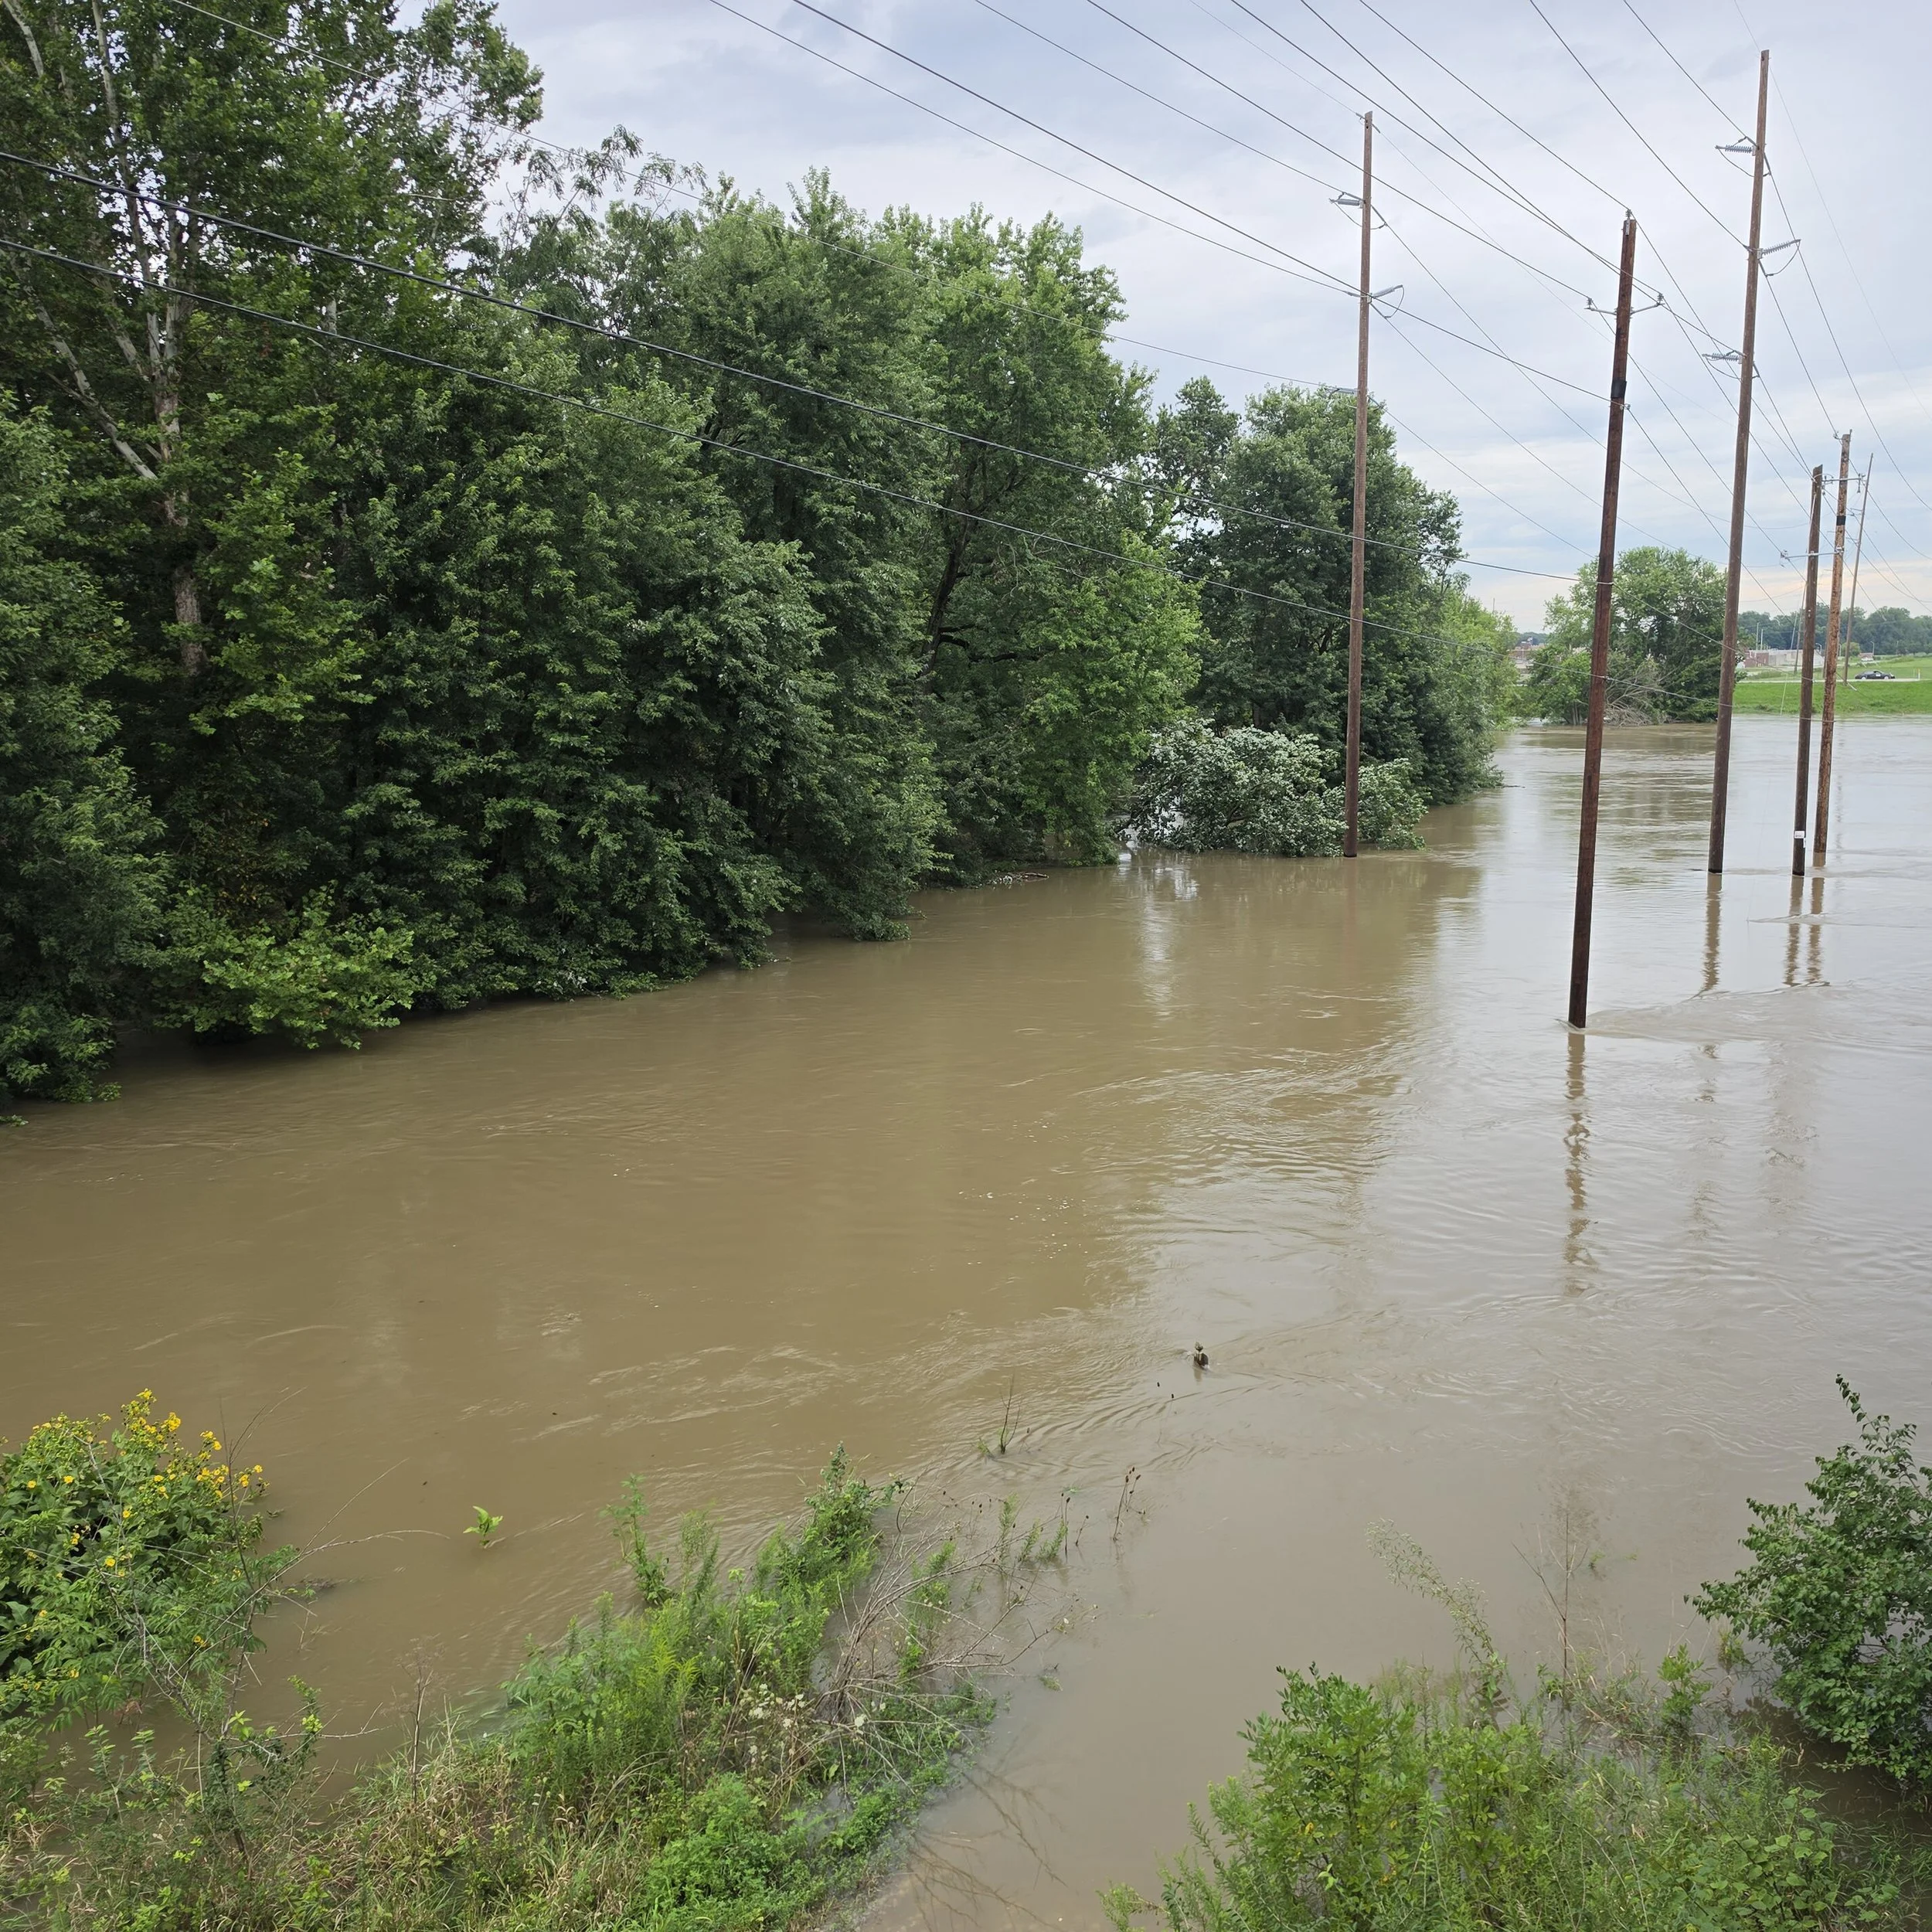
Historic flooding across Indiana raises mold risk fast. Learn what to salvage, what to remove, and how to protect your property before remediation.
Read MoreRead this Client Alert on GHG Protocol and ISO's plan to merge into a single global carbon accounting standard. This update also covers results from the Scope 2 public consultation and early feedback on the new Actions and Market Instruments (AMI) reporting proposal. Here's what it could mean for your company's GHG reporting going forward.
Read MoreDuring the July 21, 2026 workshop, CARB provided updates on the 2026 initial regulation as well as updates to proposed rulemaking concepts for 2027. Read this Client Alert for a summary of the most important developments.
Read MoreStatute Update
Senate Enrolled Act (SEA) 277 took effect on July 1, 2026, introducing new statutory requirements for petroleum underground storage tank (UST) corrective action in Indiana. On the same day, the Indiana Department of Environmental Management (IDEM) issued a clarification letter explaining how it will implement one of the law's most significant provisions, addressing the very ambiguity KERAMIDA had raised.
Earlier this year, KERAMIDA's Lauren Nielsen, P.E., Senior Engineer, Land Services, testified before the House Environmental Affairs Committee of the Indiana General Assembly regarding Indiana SEA 277. During her testimony, Lauren highlighted the need for greater clarity around the legislation's use of the term "reportable quantity" for petroleum releases, noting that petroleum is excluded from the federal hazardous substance definitions referenced elsewhere in the statute. She continued those discussions with IDEM representatives, environmental attorneys, and other stakeholders as implementation moved forward. IDEM's July 1 clarification letter speaks directly to the point KERAMIDA identified.
Under SEA 277, IDEM cannot issue a No Further Action (NFA) determination, approve closure, or request certain institutional controls unless the commissioner has received and reviewed an evaluation of potential remedies. That requirement is triggered whenever a "reportable quantity" of released petroleum remains or may remain underground at a site.
As IDEM acknowledges, the term "reportable quantity" is not defined for petroleum USTs. Working with the statute as written, the agency has taken a practical approach: it will look to the federal UST rule at 40 CFR 280.53, which addresses reporting of petroleum spills exceeding 25 gallons, for interpretive guidance. Because it is often not feasible to quantify how much petroleum was actually released, IDEM will treat any petroleum release-related chemical (RRC) remaining above its Risk-based Closure Guide (the "R2," a nonrule policy document) Published Levels as triggering the requirement to submit an evaluation of closure options, environmental deed restrictions, and remediation methods, together with estimated costs and timeframes.
IDEM has also updated State Form #55439 and State Form #55441 to reflect the new statutory requirements, a welcome development. Prior versions required the certifying environmental professional to attest that submittals complied with 329 IAC 9-5-5.1 and 329 IAC 9-5-6, sections that were repealed in 2023 and replaced by incorporation of the federal 40 CFR Part 280 requirements. The updated forms resolve a real practical problem for the professionals who sign these submittals. Copies are available on the IDEM forms page.
KERAMIDA advocated during the legislative session for a clear definition of "reportable quantity." That clarity was not written into the statute, but the requirement is now law. Importantly, though, a requirement to evaluate potential remedies is not a mandate to implement them. IDEM's own R2 is built around determining whether a remedy is actually necessary to control an unacceptable risk to human health or the environment, and under that framework, remedies are selected only where warranted. An exceedance of a generic, published screening level is the starting point for a risk evaluation, not the conclusion of one.
That distinction matters for clients. A broad evaluation requirement could tempt some consultants to recommend extensive investigation, monitoring, and active cleanup that site conditions do not justify. KERAMIDA takes the opposite approach. We apply the best available science to determine whether corrective action is genuinely necessary, recognizing that it is warranted only when a release currently poses, or will foreseeably pose, an unacceptable risk. In many cases, natural source zone depletion (NSZD), which is the natural biodegradation, dissolution, and volatilization that steadily reduces petroleum in the subsurface, removes contaminant mass at rates that meet or exceed engineered remediation, and the Interstate Technology and Regulatory Council (ITRC) recognizes it as a legitimate stand-alone or supporting remedy where exposure risks are controlled. Where natural attenuation processes such as NSZD will achieve remediation objectives within an acceptable timeframe, aggressive engineered systems are often neither necessary nor the most sustainable option.
For petroleum UST owners, operators, consultants, and contractors, IDEM's clarification offers valuable insight into the agency's expectations under the new law and the additional information that may now be required before site closure. It also raises the stakes on choosing a consultant who scopes work to actual risk. Performing investigation, monitoring, and remediation at a site that does not need it will not only delay closure but can also needlessly draw down the Excess Liability Trust Fund (ELTF), the state fund that reimburses eligible corrective-action costs. Clients who want their obligations met efficiently and their ELTF resources conserved are well served by a risk-based approach grounded in sound science.
KERAMIDA remains committed to helping clients navigate evolving environmental requirements through technical expertise, regulatory and legislative engagement, and practical implementation strategies. Lauren's testimony and continued engagement with stakeholders reflect KERAMIDA's commitment to advancing clarity for the benefit of our clients and to ensuring that corrective action is driven by what the environment and the client actually need.
Contact Lauren at: lnielsen@keramida.com
The Biden Administration promulgated a rule in March 2024 reducing the annual National Ambient Air Quality Standard for PM2.5 from 12 µg/m³ to 9 µg/m³. Several states and other groups filed legal challenges to the new rule. The Biden EPA directed all state and local agencies to review all permit applications in progress met the new lower standard. This resulted in more onerous control and operational requirements on the permit applicants.
After the second Trump Administration took office in 2025, the Trump EPA petitioned the Court of Appeals to vacate the new 9 µg/m³ standard and revert to the old 12 µg/m³ standard. On June 26, 2026, the Court of Appeals denied the Trump EPA's petition to vacate the 9 µg/m³ standard. This means that the new 9 µg/m³ standard remains in force.
The immediate impact will be that companies applying for construction of major new facilities or expansion of existing facilities subject to New Source Review will continue to face the more onerous control and operational requirements. In the longer term, EPA and the states will be required to classify areas of the country exceeding the 9 µg/m³ standard as non-attainment areas where major new and expanded operations subject to New Source Review will be more costly or sometimes not feasible to permit.
|
Questions about your air permitting obligations? KERAMIDA's environmental permitting team is here to help.
|
The International Organization for Standardization (ISO) released a draft of its Net Zero Aligned Organizations Standard (ISO/DIS 14060) on June 17, 2026. Building on the 2022 ISO Net Zero Guidelines (IWA 42), the draft translates ISO’s early recommendations into the first internationally recognized, independently verifiable standard for corporate net zero transition planning. The draft is open for a 12-week public consultation through ISO's national member bodies, with national consensus positions expected by early September and final publication anticipated in late 2026 or early 2027.
ISO 14060 has the potential to consolidate a fragmented landscape of competing "net zero" definitions and guidance into a single, auditable framework. The draft standard sets requirements for setting science-aligned targets, publishing a transition plan within two years of a net-zero commitment, and demonstrating verifiable progress. Notably, it restricts carbon credits to residual emissions rather than counting them toward reduction targets, requires front-loaded reductions against a cumulative GHG budget, and applies a significance test for determining which Scope 3 categories warrant formal targets. Its release one week after SBTi's Corporate Net Zero Standard V2.0 signals a broader convergence on what credible organizational net zero requires.
For organizations, ISO 14060 offers a path toward transition plans that are defensible under real scrutiny rather than treated as voluntary pledges. KERAMIDA will continue to monitor the standard's development through the consultation period and will provide updates as it advances toward final publication.
Questions about how ISO 14060 may affect your organization’s net-zero strategy or transition planning? Contact KERAMIDA to speak with one of our sustainability experts.
The California Air Resources Board (CARB) is proposing to defer the current reporting deadline for CA SB 253 from August 10, 2026, to November 10, 2026. The regulation is undergoing revisions, and once the public comment period concludes, the deadline extension will become final.
Read the full announcement from CARB: California Corporate Greenhouse Gas Reporting: Notice of Upcoming Rulemaking Update to Further Clarify Requirements and Deferring 2026 Reporting Deadline
Questions about your reporting obligations? Contact KERAMIDA to speak with one of our GHG experts.
The update goes beyond adding requirements. How targets are structured, how companies are categorized, and what SBTi expects between validations have changed.
For companies with existing validated targets: no action is required. Your targets remain valid through their defined timeframe.
For new submissions: V2.0 validations open in Q1 2027. Companies may continue submitting under V1.3.1 through January 31, 2028, after which all new submissions must use V2.0.
See SBTi's Summary of Main Changes document.
The European Commission has opened a public feedback period on the draft final versions of the revised European Sustainability Reporting Standards (ESRS). The consultation marks another important step in the EU’s ongoing efforts to simplify and streamline sustainability reporting requirements under the Corporate Sustainability Reporting Directive (CSRD).
The revised ESRS standards are intended to reduce the administrative burden for EU companies subject to mandatory sustainability reporting while maintaining the quality and consistency of sustainability disclosures. According to the European Financial Reporting Advisory Group (EFRAG), the proposed revisions focus on improving usability, reducing the number of datapoints (including a reduction of more than 60% in mandatory datapoints and over 70% overall), simplifying double materiality assessments, and introducing new flexibilities for companies.
In parallel, the Commission is seeking stakeholder input on voluntary sustainability reporting standards intended for small and medium-sized enterprises (SMEs) and organizations outside the scope of mandatory CSRD reporting. The voluntary framework aims to support more proportionate ESG reporting while helping smaller companies respond to increasing sustainability information requests from their reporting business partners that are subject to mandatory sustainability reporting requirements.
Stakeholders are invited to submit feedback through the European Commission’s portal until June 3. Following the close of the consultation period, the Commission is expected to adopt the two delegated acts and subsequently submit them to the European Parliament and the Council for review under the standard no-objection procedure before the standards formally enter into force.
For more information, visit the European Commission announcement:
European Commission Feedback Process on Revised Sustainability Reporting Standards
GRI and CDP have released updated mapping to help organizations align climate-related disclosures under GRI 102: Climate Change (2025) and GRI 103: Energy (2025) with CDP’s 2026 corporate questionnaire.
Read MoreCDP has officially released its 2026 questionnaires and reporting guidance, marking the start of the new disclosure cycle. The latest updates introduce changes that reflect the evolving expectations around environmental transparency and risk management.
Read MoreThe next edition of ISO 14001 Environmental Management Systems, the first since its 2015 publication, was officially launched on April 17, 2026. The 2026 revision reflects the changes that have happened since 2015 in terms of sustainability goals, climate change risk, product life cycle management, supplier management, disclosure requirements, and stakeholder scrutiny.
Read MoreThe Greenhouse Gas (GHG) Protocol is undergoing a significant, multi-year update process that will impact how organizations account for and report their GHG emissions.
Read MoreCARB has provided additional clarity regarding the SB 253 implementation during the March 23, 2026 workshop, building on the previously discussed November 18 updates.
Read MoreKERAMIDA is a global, multidisciplinary Sustainability and EHS consulting firm grounded in evidence-based research and development. Founded in 1988 by Dr. Vicky Keramida, our engineers, scientists, and technical experts advise financial institutions, industry, businesses, and governments worldwide on strategy, implementation, compliance, reporting, training, community engagement, and assurance. With offices and professionals based throughout the U.S., we provide comprehensive environmental compliance, health & safety, sustainability, and engineering services for clients worldwide.
401 North College Avenue, Indianapolis, IN 46202
(800) 508-8034 | (317) 685-6600
home | services | projects | news | insights | sustainability | careers | contact us
© 2026 KERAMIDA Inc. All Rights Reserved.
Privacy Policy